
Payment Radar
Square Upgrades Credit Card Rewards and Adds Bill Pay for Vendor Funding
Square expands its credit card program with higher rewards on bill pay and a new feature allowing merchants to pay vendors regardless of card acceptance, positioning the card as a working capital tool for SMBs.
 Payment RadarOriginal source: Squareup · linked publisher media; native reuse rights require confirmation

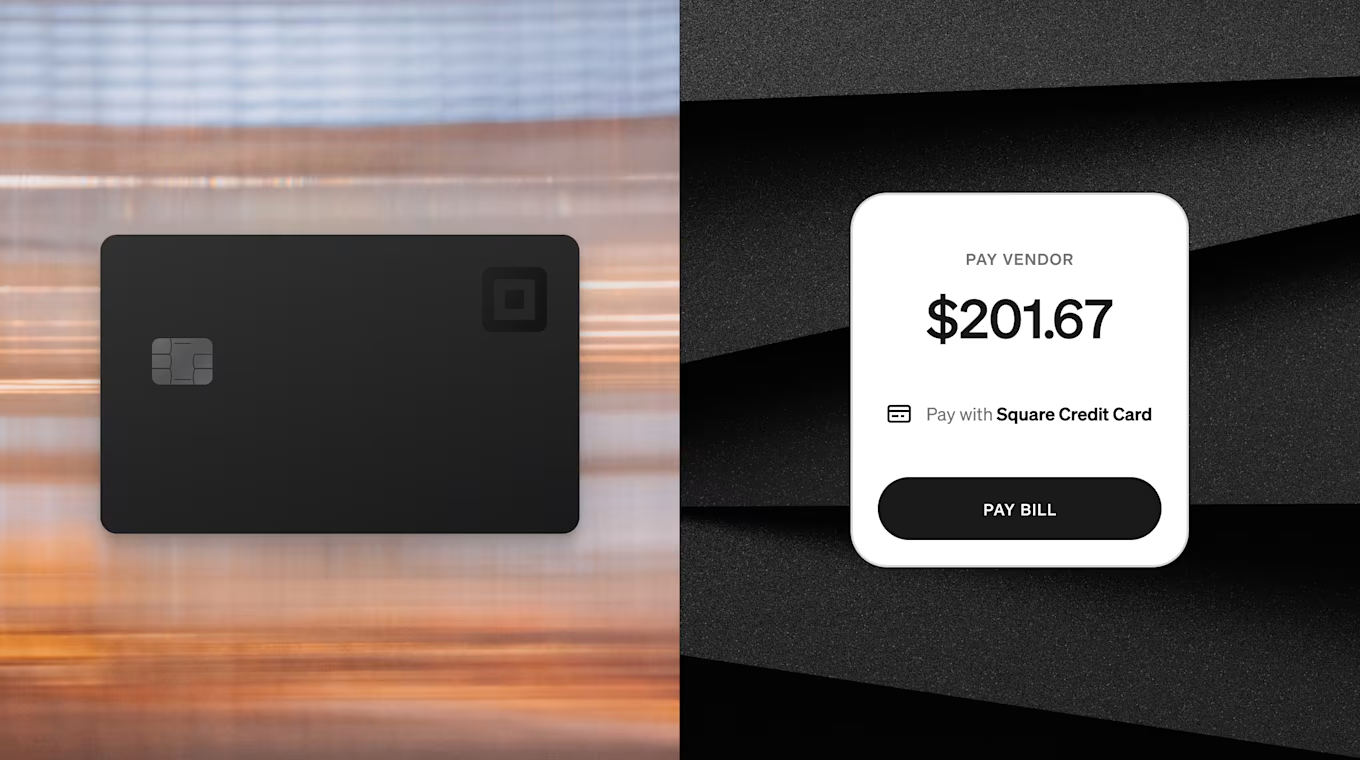
Square has expanded its Square Credit Card program, introducing a new Bill Pay feature and revised cash-back rewards designed to help small businesses manage vendor payments. The refreshed card, which runs on the American Express network, now offers unlimited 3% cash back on transactions processed through Square Bill Pay. All other purchases on the card earn 1.5% cash back.
The new Bill Pay function allows cardholders to fund payments to vendors directly from their Square Credit Card account. A key differentiator is that merchants can use this feature to pay vendors who do not accept credit cards. Square states that the 3% cash back earned on these transactions is sufficient to cover the service fees associated with the bill pay feature. The card itself carries no annual fees.
This move positions the Square Credit Card as more than just a source of working capital; it is now a tool for streamlining accounts payable. By allowing merchants to pay non-card-accepting vendors via a credit card, Square enables businesses to extend payment terms while earning rewards on the spend. This effectively turns vendor payments into a source of cash back, a feature that can improve cash flow management for tight-margin operations.
The expansion comes as payment providers increasingly compete for the small business lending and treasury market. By integrating bill pay directly into the credit card ecosystem, Square reduces friction for merchants who currently manage vendor payments through separate banking portals or checks. The ability to pay any vendor, regardless of their payment acceptance status, removes a common barrier to using credit for operational expenses.
While the primary focus is on the credit card enhancements, the broader context of small business payment innovation continues to evolve. Competitors are also exploring ways to simplify payouts and vendor payments. For instance, Dream Payments recently launched a feature called Dream Payouts, which allows businesses to issue payouts using just an email address, integrated directly into accounting software. However, Square’s latest update specifically targets the credit card and bill pay intersection, offering a direct reward mechanism for vendor funding.
For payment operators, this signals a shift in how credit products are marketed to SMBs. The value proposition is no longer just about access to funds, but about optimizing the cost of those funds through rewards and integrated payment workflows. Merchants are looking for tools that simplify their financial operations while maximizing returns on spend. Square’s update addresses both needs by tying rewards directly to the act of paying vendors.
The introduction of unlimited cash back on bill pay transactions is a significant change from previous iterations of the card. It encourages higher usage of the card for operational expenses rather than just personal or discretionary spending. This could lead to increased card volume for Square and deeper integration of its financial services into the daily operations of small businesses.
Merchants should evaluate whether the 3% cash back on bill pay outweighs the potential costs of carrying a credit card balance. If paid in full each month, the rewards can effectively subsidize vendor payment fees. However, if balances are carried, the interest costs may negate the benefits. Payment operators should advise clients to model these scenarios carefully.
The move also highlights the growing importance of embedded finance in payment platforms. By offering bill pay within the credit card product, Square is creating a more sticky ecosystem for its merchants. This integration can reduce churn and increase the lifetime value of the merchant relationship.
As competition intensifies in the SMB payments space, features like these will become standard expectations rather than differentiators. Payment operators must stay ahead by offering similar integrated solutions that simplify vendor payments and provide tangible rewards for business spend.
Comments